-
Auteur :
 Antoine C.
- Oct 12, 2026
Express Entry Proof of Funds: Getting It Right
You passed the TCF Canada with NCLC 7 or better, your profile entered the pool, and a French-language draw finally reached your CRS score. In 2026, that moment has come for tens of thousands of French speakers, with ten French-language rounds issuing around 50,500 invitations by late August and cutoffs between 382 and 420. But the Invitation to Apply (ITA) is not the finish line. You then have 60 days to submit a complete application, and one of the documents that most often causes problems is the proof of settlement funds.
This guide explains who must show funds, how much, what IRCC accepts, and how to prepare your bank documents months in advance so that a strong TCF Canada score is not undermined by a paperwork mistake.
Who Needs to Show Proof of Funds?
| Program | Proof of funds required? | Exception |
|---|---|---|
| Federal Skilled Worker Program (FSWP) | Yes | Not required if you are authorised to work in Canada and have a valid job offer |
| Federal Skilled Trades Program (FSTP) | Yes | Same exception as FSWP |
| Canadian Experience Class (CEC) | No | Exempt |
| French-language category draws | Depends on the program you qualify under | A French-speaking candidate invited under FSWP must show funds |
This is a crucial point for French speakers abroad: the French-language category is a selection category, not a separate program. If you are outside Canada, you will almost certainly be processed under the FSWP, which means proof of funds applies. If you meet both FSWP and CEC requirements, the CEC route exempts you.
How Much Money Do You Need?
IRCC sets the minimum amounts at 50% of Canada's low-income cut-off and updates them every year. The table below shows the amounts IRCC published in July 2025. Because the figures are revised annually, always check the official IRCC proof of funds page before you submit, and update your profile when the amounts change.
| Family members (including you) | Minimum funds (CAD) | Recommended buffer target (CAD) |
|---|---|---|
| 1 | $15,263 | $17,000+ |
| 2 | $19,001 | $21,000+ |
| 3 | $23,360 | $25,500+ |
| 4 | $28,362 | $30,500+ |
| 5 | $32,168 | $34,500+ |
| 6 | $36,280 | $38,500+ |
| 7 | $40,392 | $42,500+ |
| Each additional member | $4,112 | - |
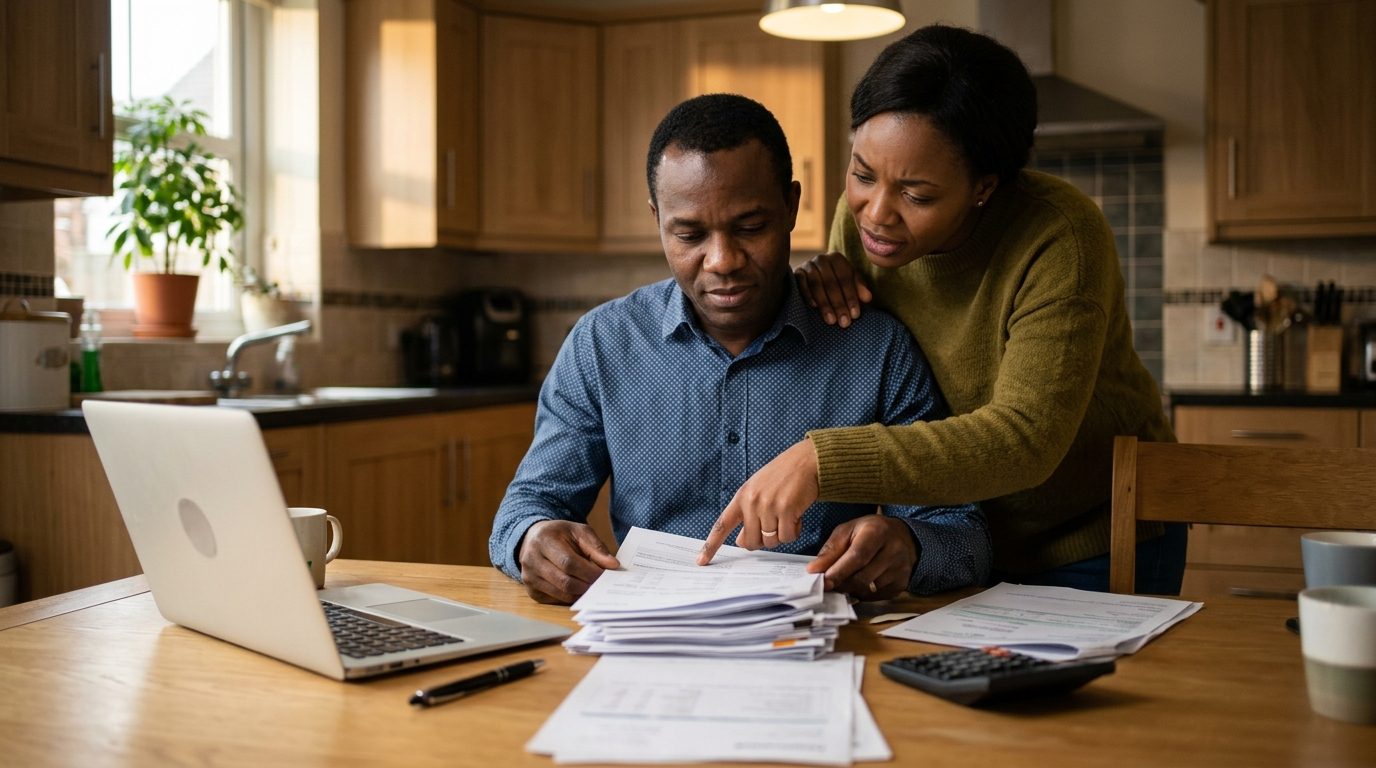
Family size is not just who travels with you. It includes you, your spouse or partner, your dependent children, and dependent children of your spouse, even if they are Canadian citizens or permanent residents, or will not immigrate with you. Undercounting family members is a classic cause of refusal.
Why a Buffer Matters
IRCC converts foreign currencies at the time of assessment. If your savings are in Moroccan dirhams, Algerian dinars, euros or CFA francs, exchange-rate fluctuations over several months of processing can push your balance below the threshold. A buffer of $1,500 to $2,000 CAD above the minimum protects you.
What Counts, and What Does Not
Accepted as proof of funds:
- Cash in current (chequing) or savings accounts
- Fixed deposits or term deposits that you can access
- Funds held in a joint account with your accompanying spouse
- Money that is available, transferable and not borrowed
Not accepted:
- Equity in real estate, land or vehicles
- Borrowed money or loans, including a loan deposited just before applying
- Funds belonging to parents, siblings or friends, even if in your account temporarily
- Investments that cannot be easily liquidated, unless converted to cash
- Cryptocurrency that has not been converted into a regular bank balance
The Bank Letter: What It Must Contain
IRCC asks for official letters from each financial institution where you hold funds. The letter must be printed on the bank's letterhead and include specific information.
Checklist for each bank letter:
- Bank name, address and contact information (phone, email)
- Your full name as it appears on your passport
- All account numbers, with the date each account was opened
- Current balance of each account
- Average balance over the past six months
- List of any outstanding debts, such as loans or credit card balances
- Date and signature or official stamp of the bank
Many banks in North Africa, West Africa and Europe are not familiar with IRCC's format. Bring a printed list of these requirements to your branch and ask for all elements in a single letter. If the letter is not in English or French, you need a certified translation.
The Six-Month History: Plan Early
IRCC looks at the average balance over six months, not just the current balance. A sudden large deposit just before applying raises questions about the source of funds. The best strategy is to consolidate your savings at least six months before you expect an invitation, ideally while you are still preparing for the TCF Canada.
A funds timeline aligned with your TCF Canada preparation:
- Month -9: Start preparing for the TCF Canada; calculate your family size and target amount
- Month -6: Consolidate savings into one or two accounts in your name; stop unnecessary transfers
- Month -4: Take the TCF Canada; keep balances stable
- Month -3: Create or update your Express Entry profile with an accurate funds figure
- ITA + 1 to 3 weeks: Request bank letters, gather statements and documents explaining any large deposits
For the broader post-test sequence, see after your TCF Canada results: the 90 critical days. For the overall budget, including test fees and settlement costs, see our complete financial planning guide.
Explaining Large Deposits
Sold a car? Received an inheritance? Got a year-end bonus? None of these is a problem if you document them. Keep the sale contract, the notarial deed, the employer's letter or the transfer receipt, and add a short letter of explanation to your application.
Illustrative case: Samuel, a Cameroonian accountant, was invited in a French-language draw with a family of three. His balance had jumped from $12,000 to $26,000 CAD equivalent two months earlier after selling a plot of land. Because he included the notarised sale deed, the bank transfer record and a one-page explanation, his proof of funds was accepted without a request for additional documents. Without them, the jump would likely have triggered questions about borrowed money.
Keep Your Profile Consistent
The funds you declare in your Express Entry profile must match reality when you apply for permanent residence. If your balance drops, update your profile. If IRCC updates the minimum amounts, verify that your declared funds still meet them. Inconsistencies between the profile and the final application can be considered misrepresentation, which carries serious consequences.
Funds and Your Arrival Budget
The proof of funds minimum is exactly that: a minimum. Real settlement costs in Canada are often higher, especially in cities with tight rental markets. First and last month's rent (where allowed), furniture, winter clothing, transport and the months before your first paycheque add up quickly. See our cost of living guide for Francophone provinces to build a realistic arrival budget.
Your Proof of Funds Action Plan
Five steps to secure this requirement:
- Confirm your program: Determine whether you will be processed under FSWP, FSTP or CEC
- Count your family correctly: Include all spouses and dependent children, accompanying or not
- Consolidate early: Six months of stable history in your own name, with a buffer above the minimum
- Brief your bank: Provide IRCC's letter requirements in advance
- Document every large deposit: Keep contracts, deeds and transfer records ready
A French-language draw can change your life with a single email. Make sure that when it arrives, your finances are as ready as your French. For a full view of how your TCF Canada score converts into CRS points, see our CRS score simulator guide.
0 Commentaires
aucun commentaire
Soyez le premier a partager votre avis !